

Money management is a lifelong journey. The financial decisions you make today can shape your lifestyle, career opportunities, retirement, and even your peace of mind decades from now. While earning more money certainly helps, avoiding common financial mistakes is often the real key to building lasting wealth.
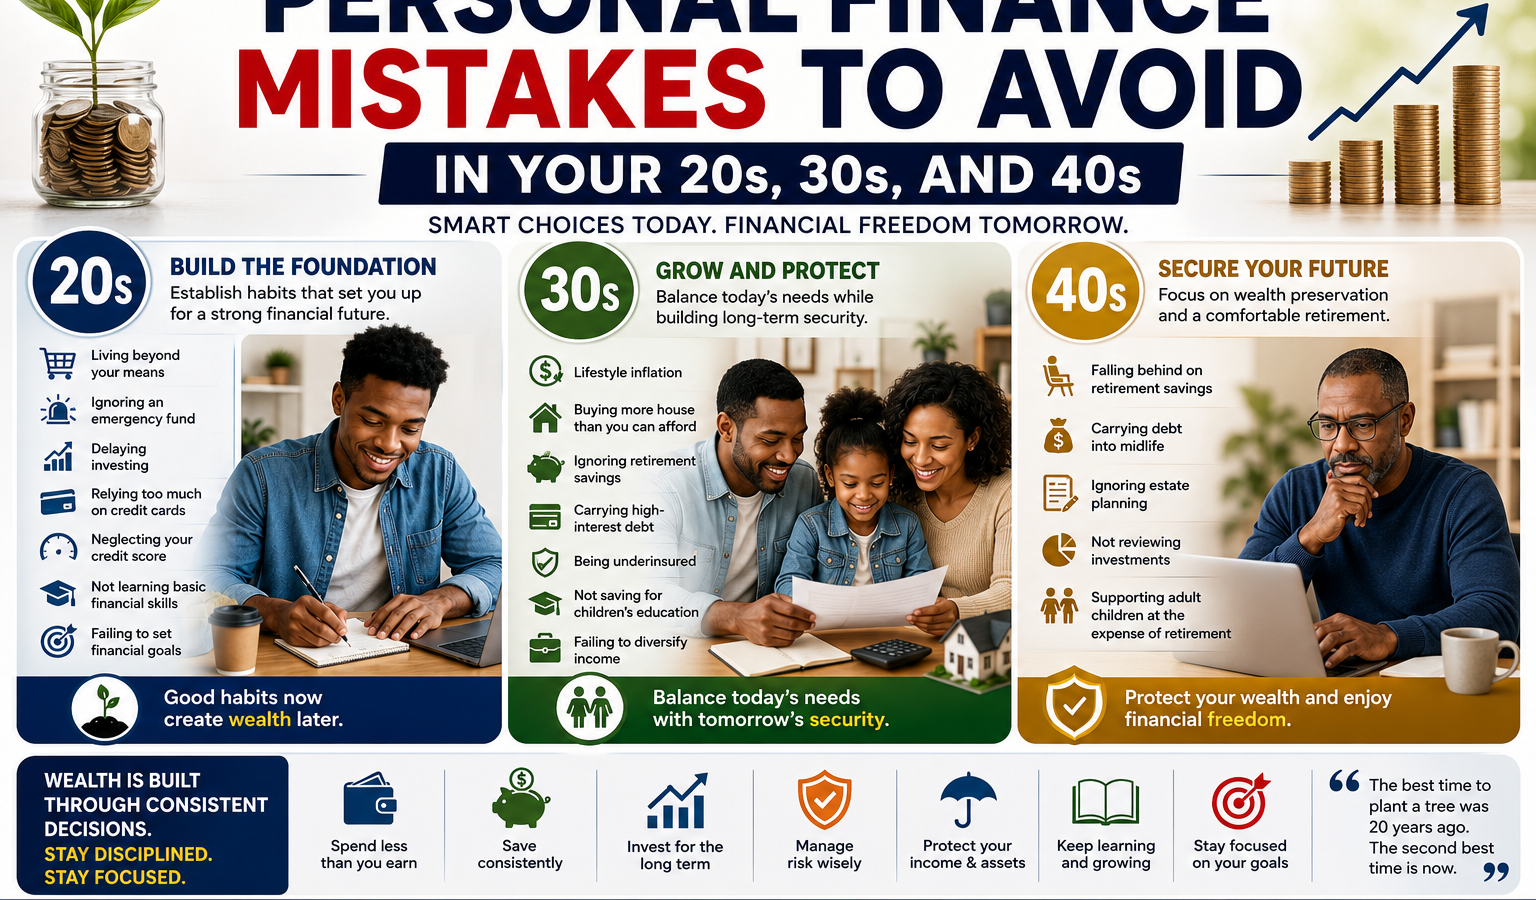
Each stage of life comes with unique opportunities and challenges. Your 20s are typically focused on education, career growth, and establishing financial independence. Your 30s often involve buying a home, raising a family, and increasing financial responsibilities. By your 40s, retirement planning, wealth preservation, and debt elimination become increasingly important.
Unfortunately, many people repeat the same costly financial mistakes at every stage of life. Some overspend to impress others. Others ignore investing until it’s too late. Many accumulate unnecessary debt or fail to prepare for emergencies.
The good news is that every financial mistake has a solution. Whether you’re just starting your career or already managing a family budget, making informed financial decisions today can significantly improve your future.
In this guide, we’ll explore the biggest personal finance mistakes to avoid in your 20s, 30s, and 40s, along with practical strategies to help you achieve financial freedom.
Why Financial Planning Matters at Every Age
Financial planning isn’t just about saving money—it’s about creating options and reducing stress. A solid financial plan helps you:
- Build wealth consistently over time.
- Prepare for unexpected emergencies.
- Reduce reliance on debt.
- Achieve major life goals such as buying a home or starting a business.
- Retire comfortably.
- Protect your family from financial hardship.
One of the greatest advantages you have is time. The earlier you develop healthy financial habits, the more powerful compound growth becomes. Even modest, consistent investments can grow substantially over decades.
Successful financial planning doesn’t require a high income. It requires discipline, consistency, and informed decision-making.
Financial Mistakes to Avoid in Your 20s
Your twenties are one of the most important decades financially. The habits you develop now often determine your financial future.
1. Living Beyond Your Means
Receiving your first paycheck can be exciting. Unfortunately, many young adults quickly increase their spending to match or exceed their income.
Common examples include:
- Financing expensive cars
- Renting luxury apartments
- Buying designer clothing
- Frequent dining out
- Expensive vacations
- Impulse online shopping
While these purchases may provide temporary satisfaction, they often delay wealth building.
Better Approach
Instead of increasing your lifestyle every time your income grows:
- Create a realistic monthly budget.
- Save before spending.
- Avoid unnecessary subscriptions.
- Track every expense.
- Focus on long-term financial goals instead of short-term gratification.
2. Ignoring an Emergency Fund
Unexpected expenses happen to everyone.
Examples include:
- Medical emergencies
- Job loss
- Car repairs
- Home repairs
- Family emergencies
Without emergency savings, many people rely on high-interest credit cards or personal loans.
Better Approach
Aim to save:
- At least 3–6 months of essential living expenses.
- Keep the money in a high-yield savings account or other easily accessible account.
- Build the fund gradually through automatic monthly transfers.
3. Delaying Investing
One of the biggest financial mistakes in your 20s is assuming you have “plenty of time.”
Time is your greatest investment advantage.
Starting early allows your investments to benefit from decades of compound growth.
Even relatively small monthly contributions can grow into substantial wealth over time because investment earnings generate additional earnings year after year.
Better Approach
- Start investing as early as possible.
- Invest consistently, even if the amount seems small.
- Diversify your investments.
- Focus on long-term growth instead of trying to time the market.
4. Depending Too Much on Credit Cards
Credit cards can be useful financial tools—but only when used responsibly.
Problems arise when people:
- Carry balances month after month.
- Make only minimum payments.
- Use credit for everyday living expenses.
- Accumulate multiple credit cards.
High-interest debt can quickly become overwhelming.
Better Approach
- Pay your balance in full whenever possible.
- Never spend more than you can afford to repay.
- Maintain a good credit score by paying on time.
- Use credit to build financial credibility—not to fund an unaffordable lifestyle.
5. Neglecting Your Credit Score
Your credit score is more than just a number—it influences your financial opportunities. A strong credit history can help you qualify for better interest rates on loans, credit cards, and mortgages, while a poor score can make borrowing more expensive.
Common Credit Score Mistakes
- Missing payment due dates.
- Maxing out credit card limits.
- Applying for multiple credit accounts in a short period.
- Ignoring errors on your credit report.
- Closing old credit accounts without understanding the impact.
Better Approach
Build healthy credit habits by:
- Paying every bill on time.
- Keeping credit utilization below 30% of your available limit.
- Reviewing your credit report regularly for inaccuracies.
- Maintaining older credit accounts when appropriate.
A strong credit profile can save you thousands of dollars in interest over your lifetime.
6. Not Learning Basic Financial Skills
Many young adults enter the workforce without understanding essential financial concepts such as budgeting, taxes, investing, insurance, or retirement planning.
Without this knowledge, it’s easier to make costly decisions or fall for financial scams.
Better Approach
Invest time in learning about:
- Personal budgeting
- Investing fundamentals
- Taxes
- Insurance
- Retirement planning
- Debt management
- Financial goal setting
Financial education is one of the highest-return investments you can make.
7. Failing to Set Financial Goals
Without clear goals, it’s easy to spend money without purpose.
Examples of Financial Goals
- Build a $10,000 emergency fund.
- Save for a home down payment.
- Pay off student loans.
- Start investing for retirement.
- Launch a business.
- Travel without going into debt.
Better Approach
Use SMART goals:
- Specific
- Measurable
- Achievable
- Relevant
- Time-bound
Review your progress every few months and adjust as your priorities change.
Financial Mistakes to Avoid in Your 30s
By your 30s, your income may be higher, but so are your responsibilities. This is often the decade of buying a home, getting married, raising children, or advancing your career. Managing these responsibilities wisely is essential for long-term financial security.
1. Lifestyle Inflation
A promotion or salary increase often leads to higher spending instead of higher saving.
Examples include:
- Upgrading to a luxury vehicle.
- Buying a larger home than necessary.
- Taking expensive vacations.
- Purchasing premium gadgets.
- Increasing discretionary spending.
While it’s natural to enjoy your success, allowing expenses to rise as quickly as your income can slow wealth creation.
Better Approach
Whenever your income increases:
- Increase retirement contributions.
- Boost emergency savings.
- Pay down debt faster.
- Invest the extra income before increasing discretionary spending.
Living below your means creates financial flexibility and accelerates wealth building.
2. Buying More House Than You Can Afford
Homeownership is a major milestone, but purchasing beyond your budget can create years of financial strain.
Many buyers focus only on the monthly mortgage payment while overlooking additional costs such as:
- Property taxes
- Home insurance
- Maintenance and repairs
- Utilities
- Homeowners association fees
Better Approach
Choose a home that fits comfortably within your budget, allowing room to continue saving and investing while handling unexpected expenses.
Remember, a home should support your financial goals—not limit them.
3. Ignoring Retirement Savings
Many people delay retirement planning because it feels decades away. Unfortunately, waiting reduces the benefits of long-term investment growth.
By your 30s, retirement savings should become a consistent financial priority.
Better Approach
- Increase retirement contributions whenever possible.
- Take advantage of employer retirement plans and matching contributions if available.
- Diversify your investment portfolio.
- Review your retirement strategy annually.
Small increases today can make a significant difference by retirement.
4. Carrying High-Interest Debt
As financial responsibilities grow, some people rely on credit cards or personal loans to cover expenses.
High-interest debt can reduce your ability to save and invest.
Better Approach
Prioritize paying off high-interest balances by:
- Paying more than the minimum payment.
- Avoiding new unnecessary debt.
- Creating a repayment plan.
- Redirecting extra income toward debt reduction.
Eliminating expensive debt improves your cash flow and strengthens your overall financial position.
5. Being Underinsured
Insurance is a vital part of a sound financial plan, yet many people either have too little coverage or the wrong type of coverage. A major illness, accident, or unexpected event can quickly derail years of financial progress.
Common Insurance Mistakes
- Choosing the cheapest policy without understanding the coverage.
- Skipping life insurance despite having dependents.
- Not reviewing policies after major life events.
- Ignoring disability or critical illness coverage where appropriate.
Better Approach
Review your insurance regularly to ensure it matches your current needs. Consider adequate coverage for your health, home, vehicle, income, and family, especially after getting married, buying a home, or having children.
6. Not Saving for Children’s Education
If you plan to support your children’s education, delaying savings can increase future financial pressure.
Education costs often rise faster than general inflation, making early planning beneficial.
Better Approach
- Start saving as early as possible.
- Contribute consistently, even with small amounts.
- Separate education savings from emergency funds and retirement savings.
- Review your plan annually and adjust contributions as your income grows.
Remember, while helping your children is admirable, avoid sacrificing your retirement security to do so.
7. Failing to Diversify Income
Relying on a single paycheck can increase financial risk. Job loss, business setbacks, or industry changes can significantly impact your finances.
Better Approach
Explore additional income opportunities such as:
- Freelancing
- Consulting
- Starting a small business
- Selling digital products
- Dividend-paying investments
- Rental property income
- Affiliate marketing
- Online content creation
Diversifying your income can strengthen your financial resilience and accelerate wealth building.
Financial Mistakes to Avoid in Your 40s
Your 40s are often your peak earning years. This decade is an excellent time to strengthen your finances, eliminate debt, and prepare for retirement.
1. Falling Behind on Retirement Savings
If retirement savings haven’t been a priority earlier, your 40s are the time to catch up.
Waiting another decade can make achieving your retirement goals much more difficult.
Better Approach
- Increase retirement contributions whenever possible.
- Review your investment allocation.
- Estimate your retirement income needs.
- Take advantage of catch-up contribution opportunities when eligible under your country’s retirement rules.
2. Carrying Debt Into Midlife
Debt that seemed manageable in your 20s or 30s can become a serious obstacle later in life.
Examples include:
- Credit card balances
- Personal loans
- Vehicle loans
- High-interest consumer debt
Better Approach
Focus on eliminating expensive debt while continuing to invest for retirement.
A debt-free lifestyle offers greater financial flexibility and peace of mind.
3. Ignoring Estate Planning
Many people believe estate planning is only for the wealthy, but everyone should have a basic plan.
Without one, your loved ones may face unnecessary legal and financial complications.
Better Approach
Consider preparing:
- A legally valid will.
- Beneficiary designations for financial accounts.
- A power of attorney where appropriate.
- Healthcare directives based on local laws.
- An organized list of important financial documents.
Consult a qualified legal professional to ensure your documents comply with your jurisdiction’s requirements.
4. Not Reviewing Investments
Investment strategies that worked in your 20s may no longer suit your goals or risk tolerance.
Better Approach
Review your portfolio at least once a year by considering:
- Asset allocation
- Diversification
- Investment costs
- Performance
- Risk exposure
- Progress toward retirement goals
Avoid making emotional investment decisions based on short-term market movements.
5. Supporting Adult Children at the Expense of Retirement
Helping adult children can be rewarding, but consistently sacrificing your own financial future may create long-term challenges.
Better Approach
Provide support within clear financial limits while keeping retirement savings a priority. A financially secure retirement reduces the likelihood that your children will need to support you later.
Universal Financial Habits That Build Wealth at Any Age
Regardless of your age, these habits can strengthen your financial future:
- Create and follow a realistic budget.
- Spend less than you earn.
- Save consistently.
- Invest for the long term.
- Maintain an emergency fund.
- Avoid unnecessary debt.
- Review financial goals annually.
- Continue learning about personal finance.
- Protect your income and assets with appropriate insurance.
- Diversify income sources where practical.
Consistency often matters more than perfection.
Frequently Asked Questions (FAQ)
What is the biggest financial mistake people make in their 20s?
Living beyond their means, delaying investing, and relying heavily on credit cards are among the most common mistakes.
Is it too late to start investing in your 40s?
No. While starting earlier offers more time for growth, investing consistently in your 40s can still significantly improve your retirement outlook.
How much should I save for emergencies?
A common guideline is to maintain enough savings to cover three to six months of essential living expenses, though individual needs vary.
Should I pay off debt or invest first?
It depends on the type of debt, interest rates, and your overall financial goals. High-interest debt is often a priority, while continuing to save for retirement—especially if employer matching is available—can also be beneficial.
How often should I review my financial plan?
Review your financial plan at least once a year and after major life events such as marriage, the birth of a child, changing jobs, or purchasing a home.
Key Takeaways
- Financial habits formed early can have a lasting impact.
- Avoid lifestyle inflation as your income grows.
- Build and maintain an emergency fund.
- Start investing as early as possible and stay consistent.
- Manage debt responsibly and avoid unnecessary borrowing.
- Protect yourself and your family with appropriate insurance.
- Plan for retirement well before you expect to retire.
- Review and adjust your financial strategy regularly.
- Focus on long-term financial discipline rather than short-term gratification.
Conclusion
Building wealth isn’t about making perfect financial decisions—it’s about making consistently smart ones over time. Every decade brings new opportunities and responsibilities, but the core principles remain the same: spend wisely, save consistently, invest for the future, and protect what you’ve built.
Whether you’re in your 20s laying the foundation, your 30s balancing growing responsibilities, or your 40s preparing for retirement, avoiding common financial mistakes can help you achieve greater financial stability and freedom. Start where you are, make one positive change today, and let those small, consistent actions compound into lasting financial success.




